Imagine waiting a whole year to buy a home, only to find that mortgage rates are about the same as they are today. It might feel frustrating, but that's a very real possibility.
A lot of people are putting their plans on hold because they think much lower mortgage rates are just around the corner. But based on today's forecasts, that may not happen. That's something worth knowing before you decide your next move.
Let's take a look at why experts don't expect mortgage rates to drop dramatically and explore the options that could still help you buy a home. Even if rates stay where they are, you still have ways to make your move. Here's how.
1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way
If you're waiting for mortgage rates to come down, you're definitely not alone. A recent survey from Clever Best Interest found that 42% of people believe rates will drop below 5% this year.
The challenge is that the experts who follow mortgage rates every day aren't expecting that to happen.
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all point to mortgage rates staying fairly steady, likely in the low to mid 6% range through at least the middle of 2027, as shown in the graph below.
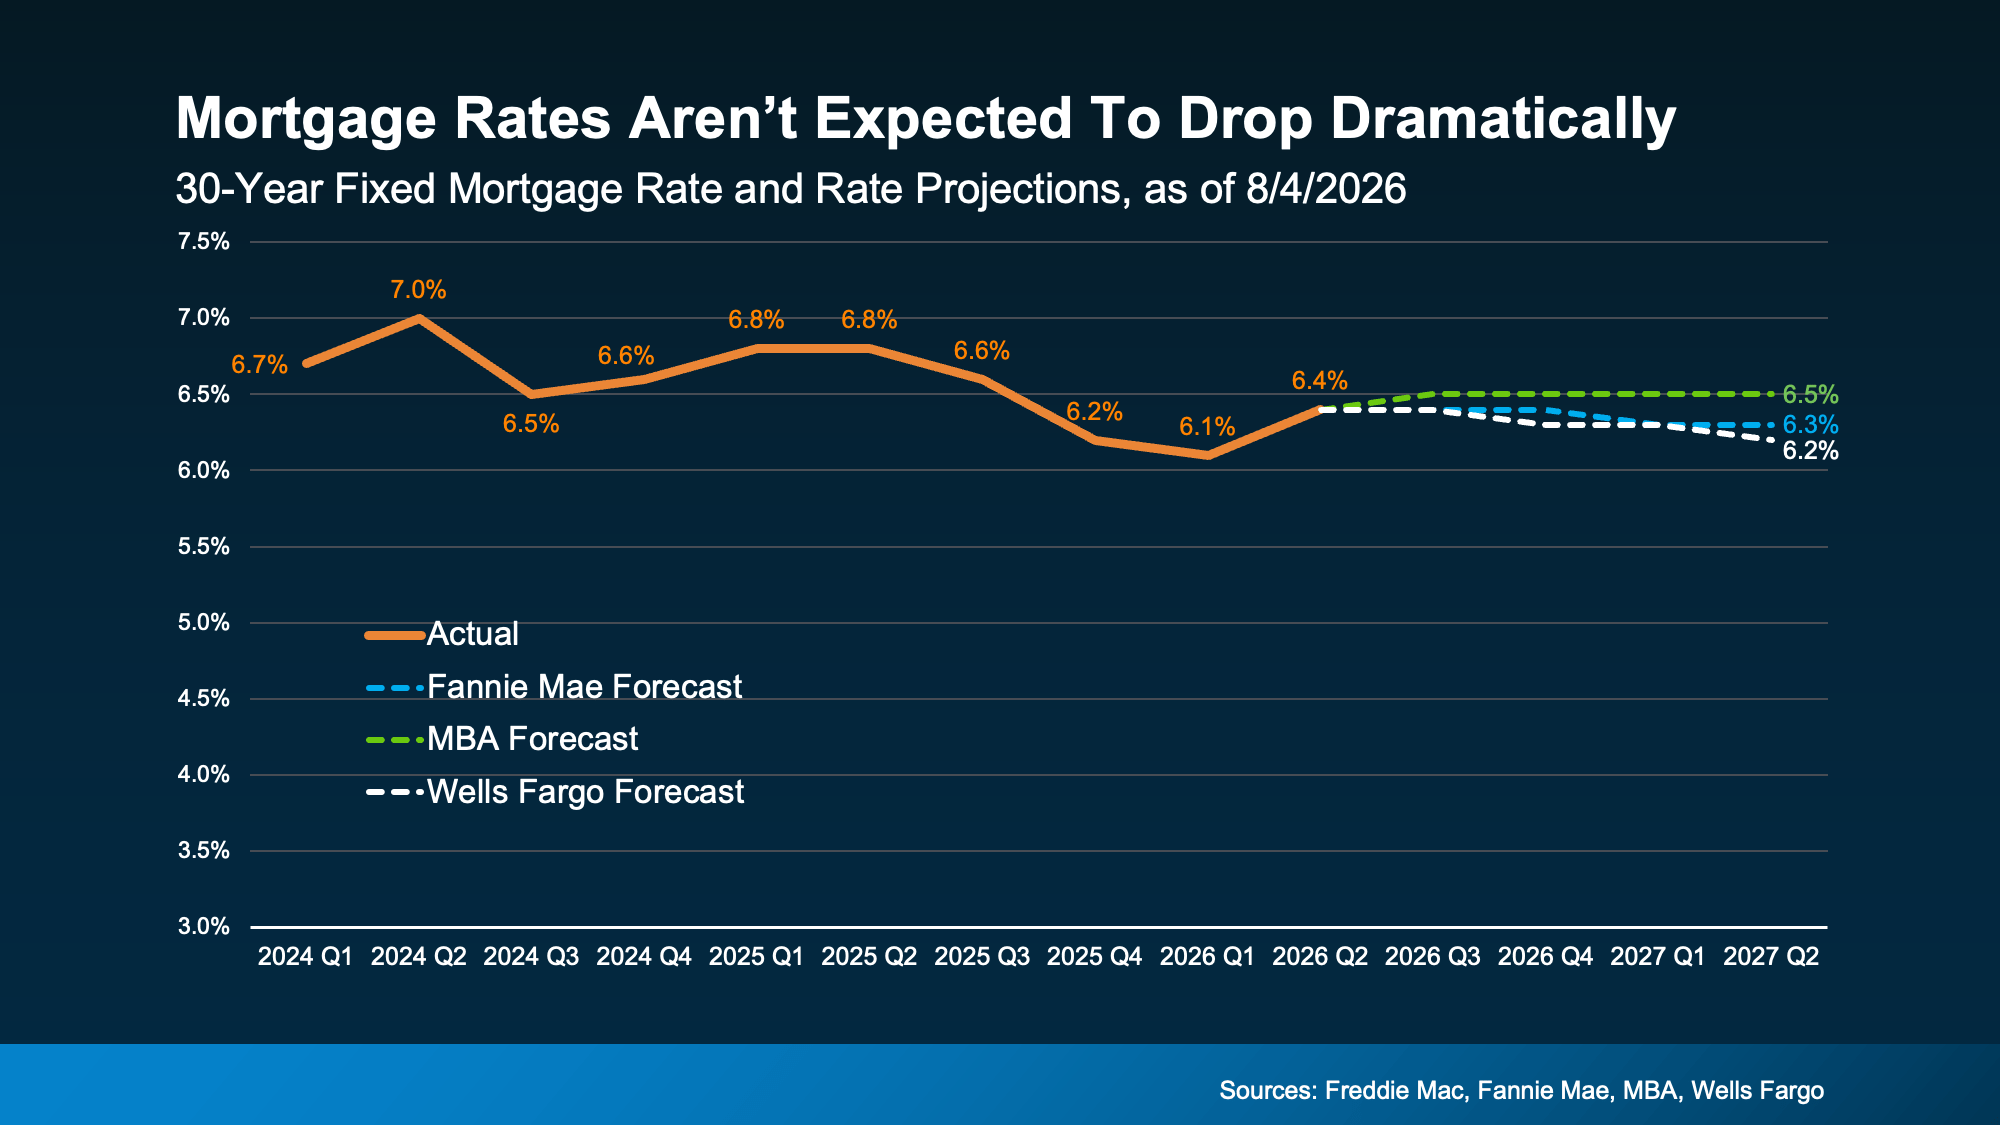
Mortgage rates are affected by inflation, the economy, Treasury yields, Federal Reserve policy, global events, and many other factors. Right now, those pieces aren't lining up for the big rate drop that many buyers are hoping to see.
Could mortgage rates come down a little? Absolutely. But if you're waiting for a much bigger drop, today's forecasts suggest it could take a lot longer than you expect.
2. Inflation Is Still Elevated And That’s Working Against Lower Rates
One of the biggest reasons experts don't expect mortgage rates to fall much is inflation. In general, when inflation stays high, it's much harder for mortgage rates to come down.
One of the main reasons experts don't expect mortgage rates to fall much is inflation. When inflation remains high, it usually keeps mortgage rates higher too.
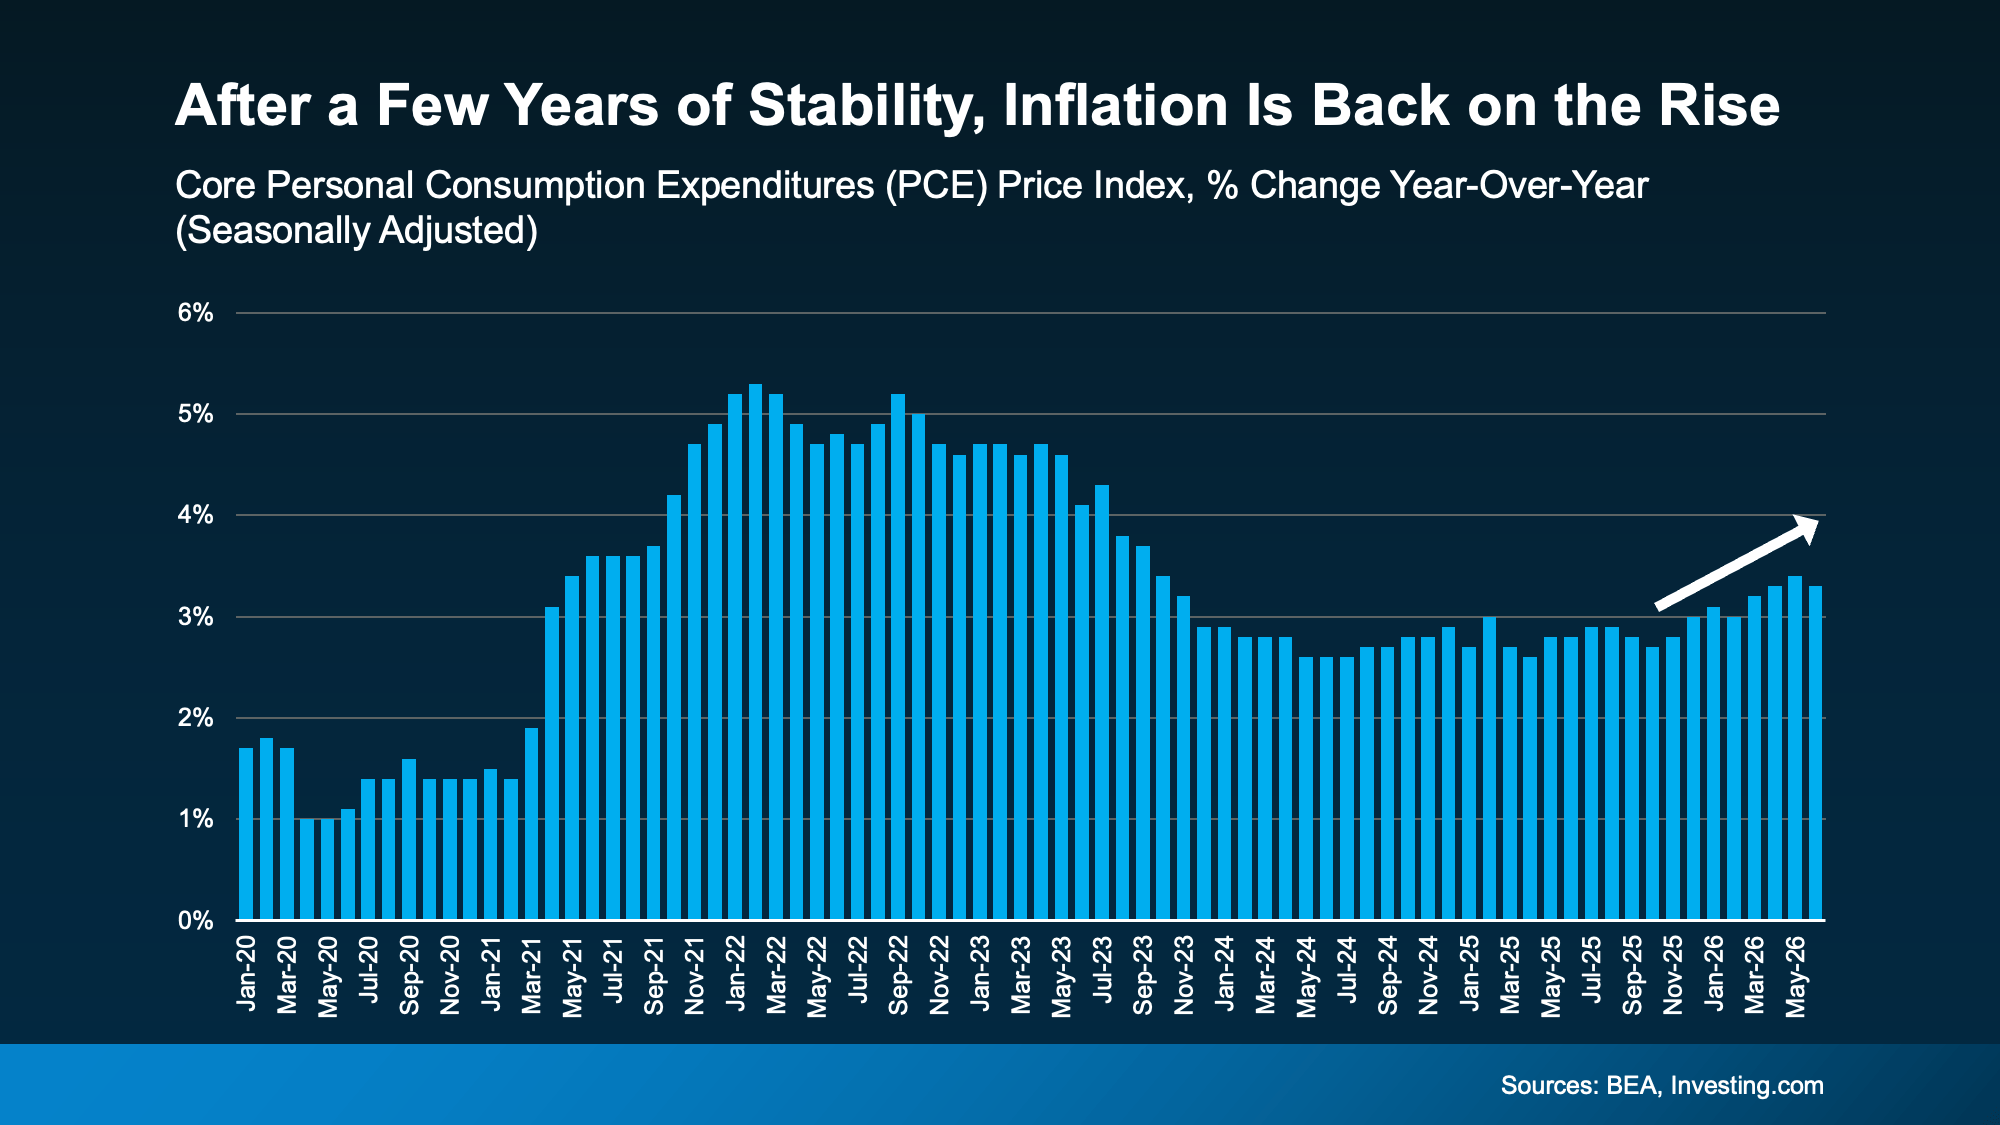
In other words, one of the key factors needed for much lower mortgage rates just isn't in place right now. That's why experts aren't expecting the significant drop that so many buyers are hoping to see.
3. Today’s Rates Aren’t High, They’re "Normal"
And this may be the biggest mindset shift of all. While today's mortgage rates may seem high compared to a few years ago, they're actually closer to what's considered normal.
Historically, mortgage rates have spent most of their time between about 5% and 10%. According to Freddie Mac, today's rates are still within that normal range. They just feel high because many of us remember the record low rates during the pandemic, as shown in the graph below.
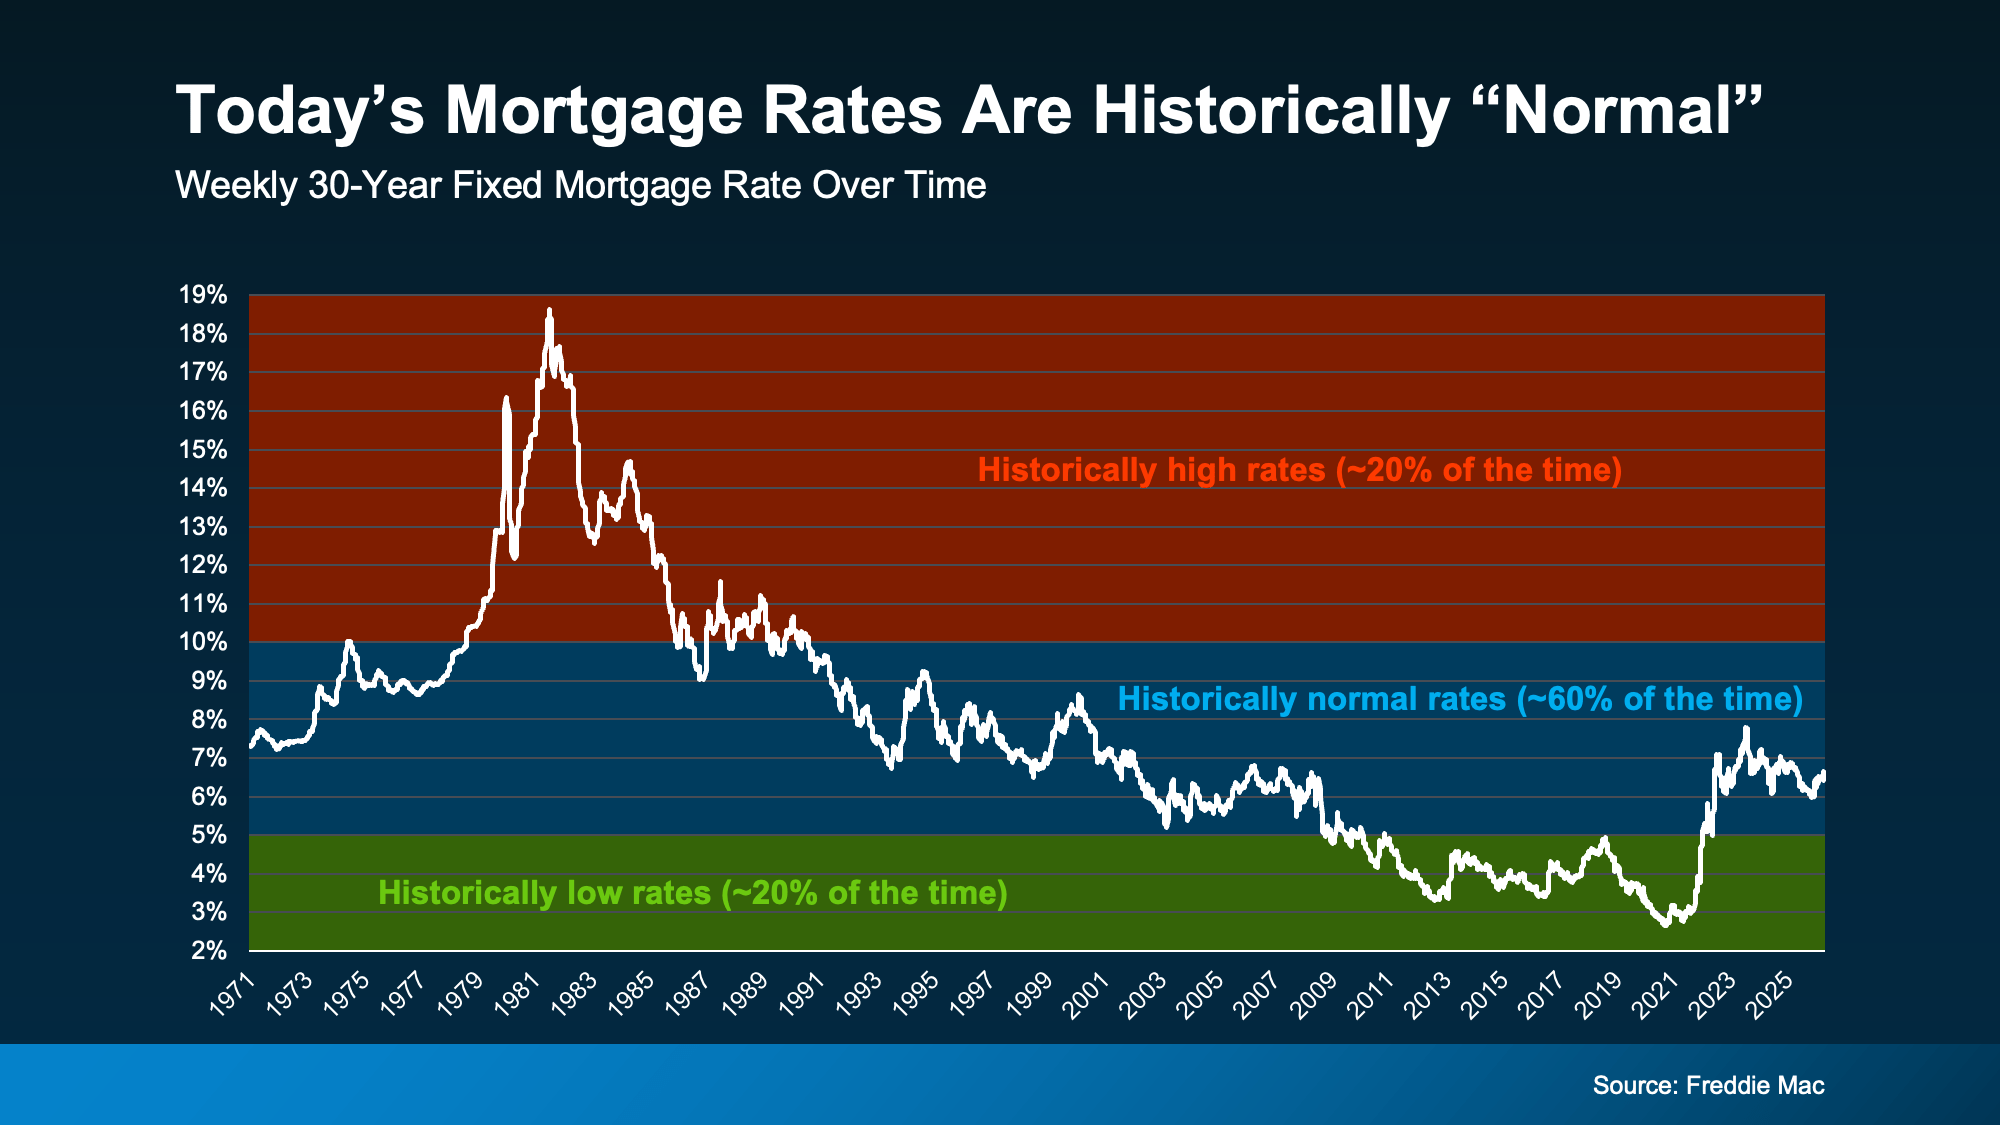
That doesn't suddenly make a 6% mortgage feel exciting, but it does put things into perspective. Waiting for those super low rates to come back may not be the most realistic strategy.
So... What Should You Do Instead?
None of this means you have to buy a home today. You don't. But if a change in your life means you're ready to move, there are still ways to make homeownership more affordable without waiting for mortgage rates to drop.
• Consider a newly built home. Many builders are offering incentives to attract buyers, including price reductions, lower mortgage rates, free upgrades, and more.
• Ask about an adjustable rate mortgage (ARM). If you don't plan to stay in the home long term, an ARM could offer a lower initial rate than a traditional 30 year fixed mortgage. It isn't right for everyone, but it's worth asking your lender if it makes sense for your situation.
• Explore mortgage rate buydowns. You may be able to pay an upfront cost to lower your mortgage rate and reduce your monthly payment without waiting for rates to fall.
• See if an assumable mortgage is an option. With an assumable mortgage, you may be able to take over the seller's existing loan and its potentially lower interest rate.
The important thing is, don't assume waiting is your only option.
Bottom Line
If you've been holding off on your home search because you expect mortgage rates to drop significantly soon, it may be time to rethink that strategy.
Let’s connect so you can have an expert walk you through your options and help you decide whether waiting really puts you in a better position or simply keeps you on the sidelines longer.