You may have seen headlines talking about using your 401(k) for a home down payment. If you’re trying to make buying a home more affordable, you might be wondering if tapping into those savings could help you get there sooner.
The bottom line is, using your retirement savings is a big decision. Take some time to consider all your options, and talk with a financial professional before making any moves.
Why Dipping into a 401(k) Can Be Tempting
According to Empower, many Americans have built up a solid amount of retirement savings. For people in their 40s through 60s, the median 401(k) balance is in the six figures, as the graph below shows.
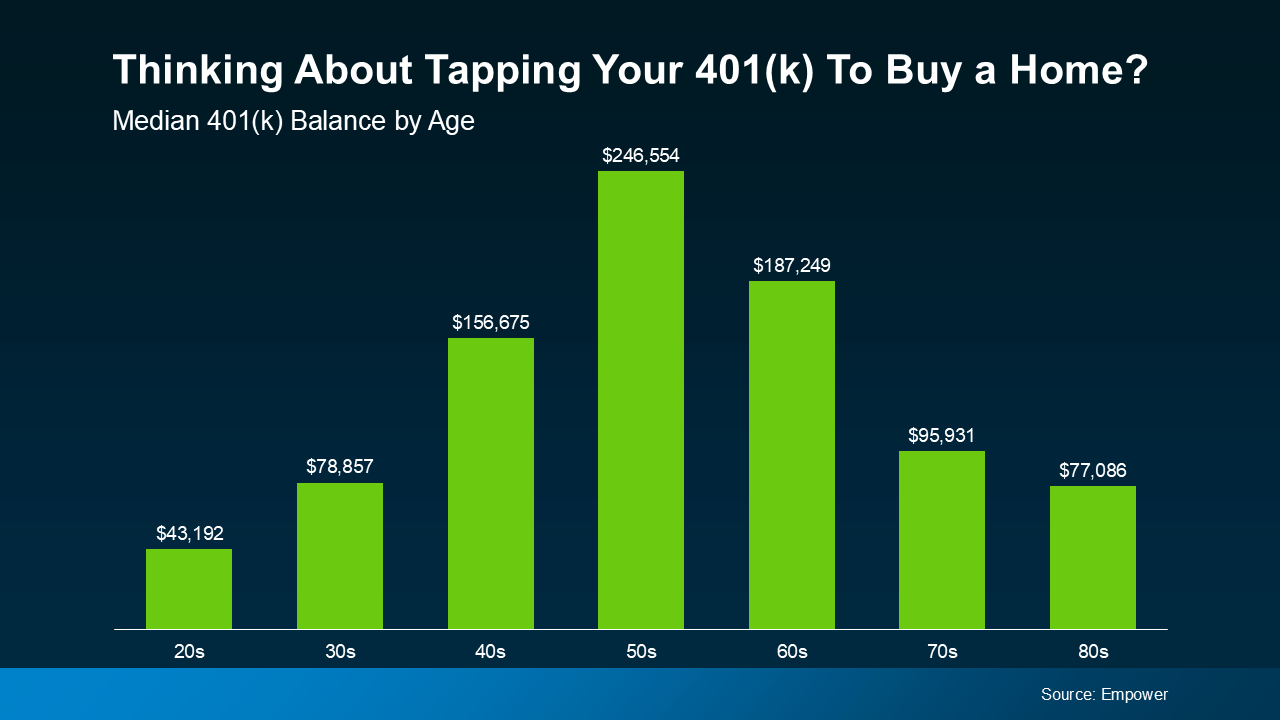
And when you’ve built up a nice amount of savings and your dream home is within reach, using some of that money can feel like an easy decision.
But using your retirement savings to buy a home could come with penalties and leave you with less money for the future. That’s why it’s worth looking at other down payment options first. As Redfin points out:
““If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.”
”
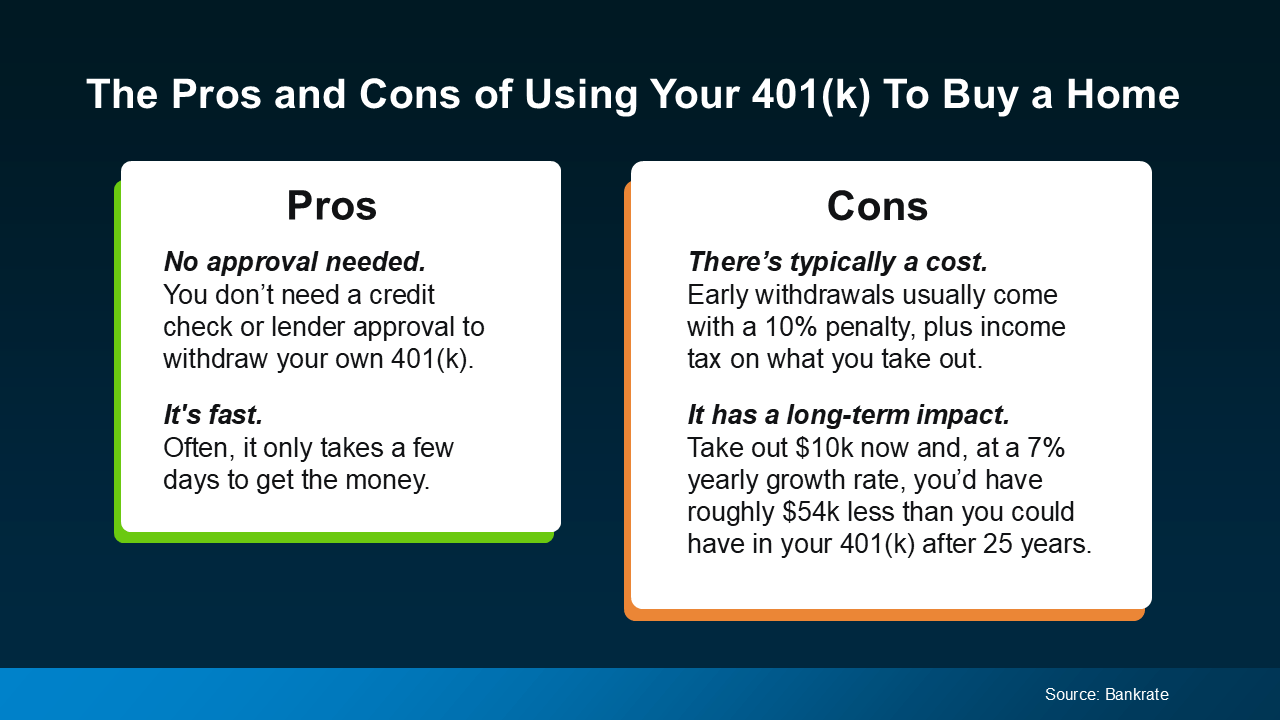
Before making a decision, talk with a financial advisor who can help you weigh the potential benefits against the risks. Bankrate highlights a few of each in the visual below:
Other Options Worth Exploring First
Your 401(k) isn’t your only option when it comes to buying a home. Redfin highlights a few other ways to cover your down payment that are worth exploring before you make a decision:
• Low and No Down Payment Loans: FHA loans can allow qualified buyers to put down as little as 3.5%, depending on their credit score.
• Down Payment Assistance Programs: There are many local and national programs that can help with your down payment or closing costs, potentially making homeownership more affordable.
Make a Plan Before You Make a Move
No matter which option you choose, it’s a good idea to talk with a financial professional first. The smartest move is to have a solid plan in place and work with the right experts before you start your journey toward homeownership. As NerdWallet puts it:
““Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.”
”
Bottom Line
Affordability can be a challenge, but that doesn’t mean using your 401(k) is your only option when it comes to buying a home.
If you’re thinking about using your 401(k) for a down payment, take a look at all your options and talk with a trusted financial advisor first. They can help you create a plan that fits your goals and your budget.